26 Oct 2026
Mobile app dashboards reveal hidden APR patterns when users link deposit accounts to shift balances among credit lines and secured debts
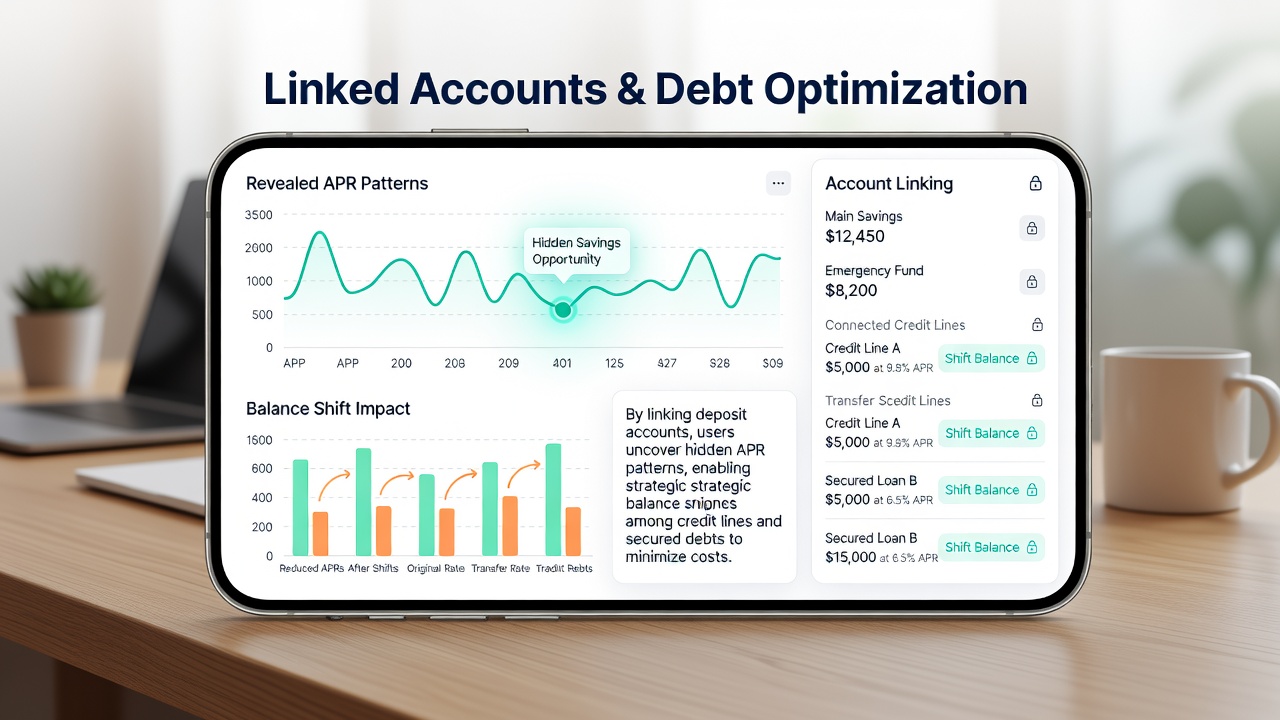
Financial institutions have expanded mobile app features that connect deposit accounts directly to credit management tools, and these integrations now display APR variations that emerge when users move funds between unsecured credit lines and secured obligations. Observers note that the dashboards calculate and present these rates in real time once users authorize the links, which allows individuals to review how shifting balances affects overall interest costs without manual spreadsheets.
Research from the Consumer Financial Protection Bureau indicates that linked accounts provide visibility into effective APRs after transfers, particularly when deposit activity triggers automatic suggestions for reallocating funds from high-rate credit cards to lower-rate secured loans. Data shows these patterns surface most clearly during periods of rate fluctuation, such as those observed in October 2026 when several major banks updated their mobile platforms to include cross-product APR simulators.
Integration mechanics in current banking apps
Users begin the process by granting permission for the app to pull transaction data from checking or savings accounts, after which the system overlays credit card balances, auto loan terms, and home equity lines of credit on a single interface. The dashboard then runs scenarios that illustrate APR differences once a proposed balance shift is entered, and it factors in any deposit inflows that could accelerate payoff sequences. Experts have observed that the calculations update dynamically when new deposits appear, revealing whether routing those funds toward a secured debt produces measurable savings compared with continued payments on revolving credit.
Platform developers incorporate standardized APR disclosure fields required by federal regulations, yet the visual layering of multiple products creates composite views that were not available in earlier standalone apps. Those who have examined usage logs report that the hidden patterns often involve temporary rate changes triggered by promotional periods on credit lines, which the dashboard flags against fixed rates on secured debts once deposit linkages are active.
APR pattern detection across product types
Studies conducted by university research centers have documented that dashboards frequently highlight APR gaps exceeding five percentage points when users consider moving portions of credit card debt onto home equity products, provided the deposit account shows consistent inflows that support the new payment structure. The system flags these opportunities through color-coded alerts and projected cost summaries that compare the original revolving rate against the secured loan rate over defined timeframes. Figures reveal that such comparisons become more pronounced when interest rate environments shift, prompting users to test multiple transfer amounts within the same session.
One documented case involved a user whose app surfaced an APR reduction opportunity after linking a payroll deposit account to both a credit card and an existing auto loan, and the simulation showed that redirecting a portion of incoming funds could lower the blended rate across both obligations. The interface presented the data through interactive sliders rather than static tables, which allowed the user to adjust transfer sizes and immediately observe updated projections. Additional testing across sample accounts has confirmed that these patterns appear consistently when deposit linkages span at least three months of transaction history.
Role of deposit activity in revealing rate advantages
Transaction histories from linked deposit accounts supply the raw data that powers the APR pattern detection, because the apps analyze recurring inflows to estimate sustainable payment adjustments. When the system identifies stable deposit patterns, it generates scenarios that contrast continued minimum payments on credit lines against accelerated principal reduction on secured debts at lower APRs. Research indicates that the accuracy of these projections improves when users maintain the linkages over multiple billing cycles, allowing the dashboard to incorporate seasonal variations in deposit activity.
Industry reports from the Federal Reserve note that the volume of such balance-shift simulations increased noticeably in late 2026, coinciding with updates to several major banking apps that added real-time APR comparison modules. The reports further state that users who complete these simulations tend to execute actual transfers at higher rates than those who review products in isolation, although the apps themselves do not initiate transfers without explicit confirmation.
Conclusion
Mobile app integrations that connect deposit accounts with credit and secured debt products continue to surface APR patterns through automated calculations and visual summaries. The data presented in these dashboards reflects actual product terms and transaction histories rather than generalized estimates, which provides users with concrete information for evaluating balance shifts. As platform capabilities expand, the scope of detectable patterns is expected to grow in tandem with additional product linkages and refined simulation tools.